

In Round #12: More First Brands news; Jim Chanos opines on Private Credit & First Brands; Private Credit goes to Japan; Carlyle on U.S. National Debt; Checking the math on 19,000 PE firms; Private Credit 101; Private Credit 501; Discussing indestructible CLOs; Deals!
1. First Brands First
Alright debtageeks, I know you’ve probably read 50 articles about First Brands in the last few days, but some of the stuff coming out of this debacle is just so comical and absurd, I can’t pass on it.
First, according to Reuters (Free LINK), First Brands’ creditors include at least 517 CLOs. That’s a lot of CLOs…
Second, and likely because so many CLOs included First Brands loans in their portfolios, the Ad Hoc group formed to provide DIP financing in bankruptcy included 81 lenders and holders! (See Filing - free) Can you imagine a group call?! To be fair, not all of these 81 lenders are victims of First Brands’ shenanigans. Some of them, like Diameter Capital, took a position after the loans dropped below 40 cents on the dollar, as discussed in my prior letter. They should be able to profit nicely, since the DIP that’s being put in place and already agreed to by 99% of first-lien holders, plus a majority of the other liens, is quite lucrative (See Filing - free).
Here is the summary:
The DIP has a total size of $4.4B, split between $1.1B in new-money term loans and a $3.3B creeping roll-up of first-lien term debt. It matures in 270 days, with options to extend if needed.
New Money: The $1.1B new-money piece is a multi-draw facility, with $500m available up front (some in escrow) and $600m locked in escrow until the final order comes in. Pricing is SOFR + 1.55% cash and 8.45% PIK, and lenders pocket a 10% PIK anchor premium at interim approval, plus a 5% PIK upfront fee and a 5% cash exit fee. Extensions tack on an extra 0.75% for each 45 days.
Roll- ups: There is a 3:1 creeping roll-up totaling about $3.3B, with $1.5B rolling at interim and $1.8B rolling after the final order and funding. Roll-up loans accrue at SOFR + 7% PIK. All first-lien lenders can opt in and roll their prepetition claims.
BTW, 81 lenders also means a lot of law firms, and legal fees. By the time the roll call wraps up and everyone has confirmed they are on the line, lawyers are already well in the green. Good times!
2. So, you’re telling me there’s Chanos
Jim Chanos, famed short-seller, shared his opinion on private credit with Financial Times following First Brands’ debacle (well, I guess we’re stuck with it). His quote:
I suspect we’re going to see more of these things, like First Brands and others, when the cycle ultimately reverses, particularly as private credit has put another layer between the actual lenders and the borrowers.
With the advent of private credit . . . institutions [are] putting money into this magical machine that gives you equity rates of return for senior debt exposure, should be the first red flag.
The article (Free LINK) discusses how hard it was for even the credit pros to spot the inventory financing SPEs. Goldman traders didn’t catch on to the expensive borrowing from those entities until just hours before the bankruptcy and said the details were tough to sort out. BTW, these SPEs filed for bankruptcy separately from First Brands…which is a sign of a complete mess.
3. Japan: Great Reawakening
Here are a few headlines from last week: KKR Prepares for Private Credit Boom in Japan (Free LINK); Apollo: Outlook for Japan (Free LINK); Blackstone Hits $10B Asia Fund Goal Amid PE Chill (also including Japan) (Free LINK)…Wait, what is going on in Japan?
Apparently, Japan is back.
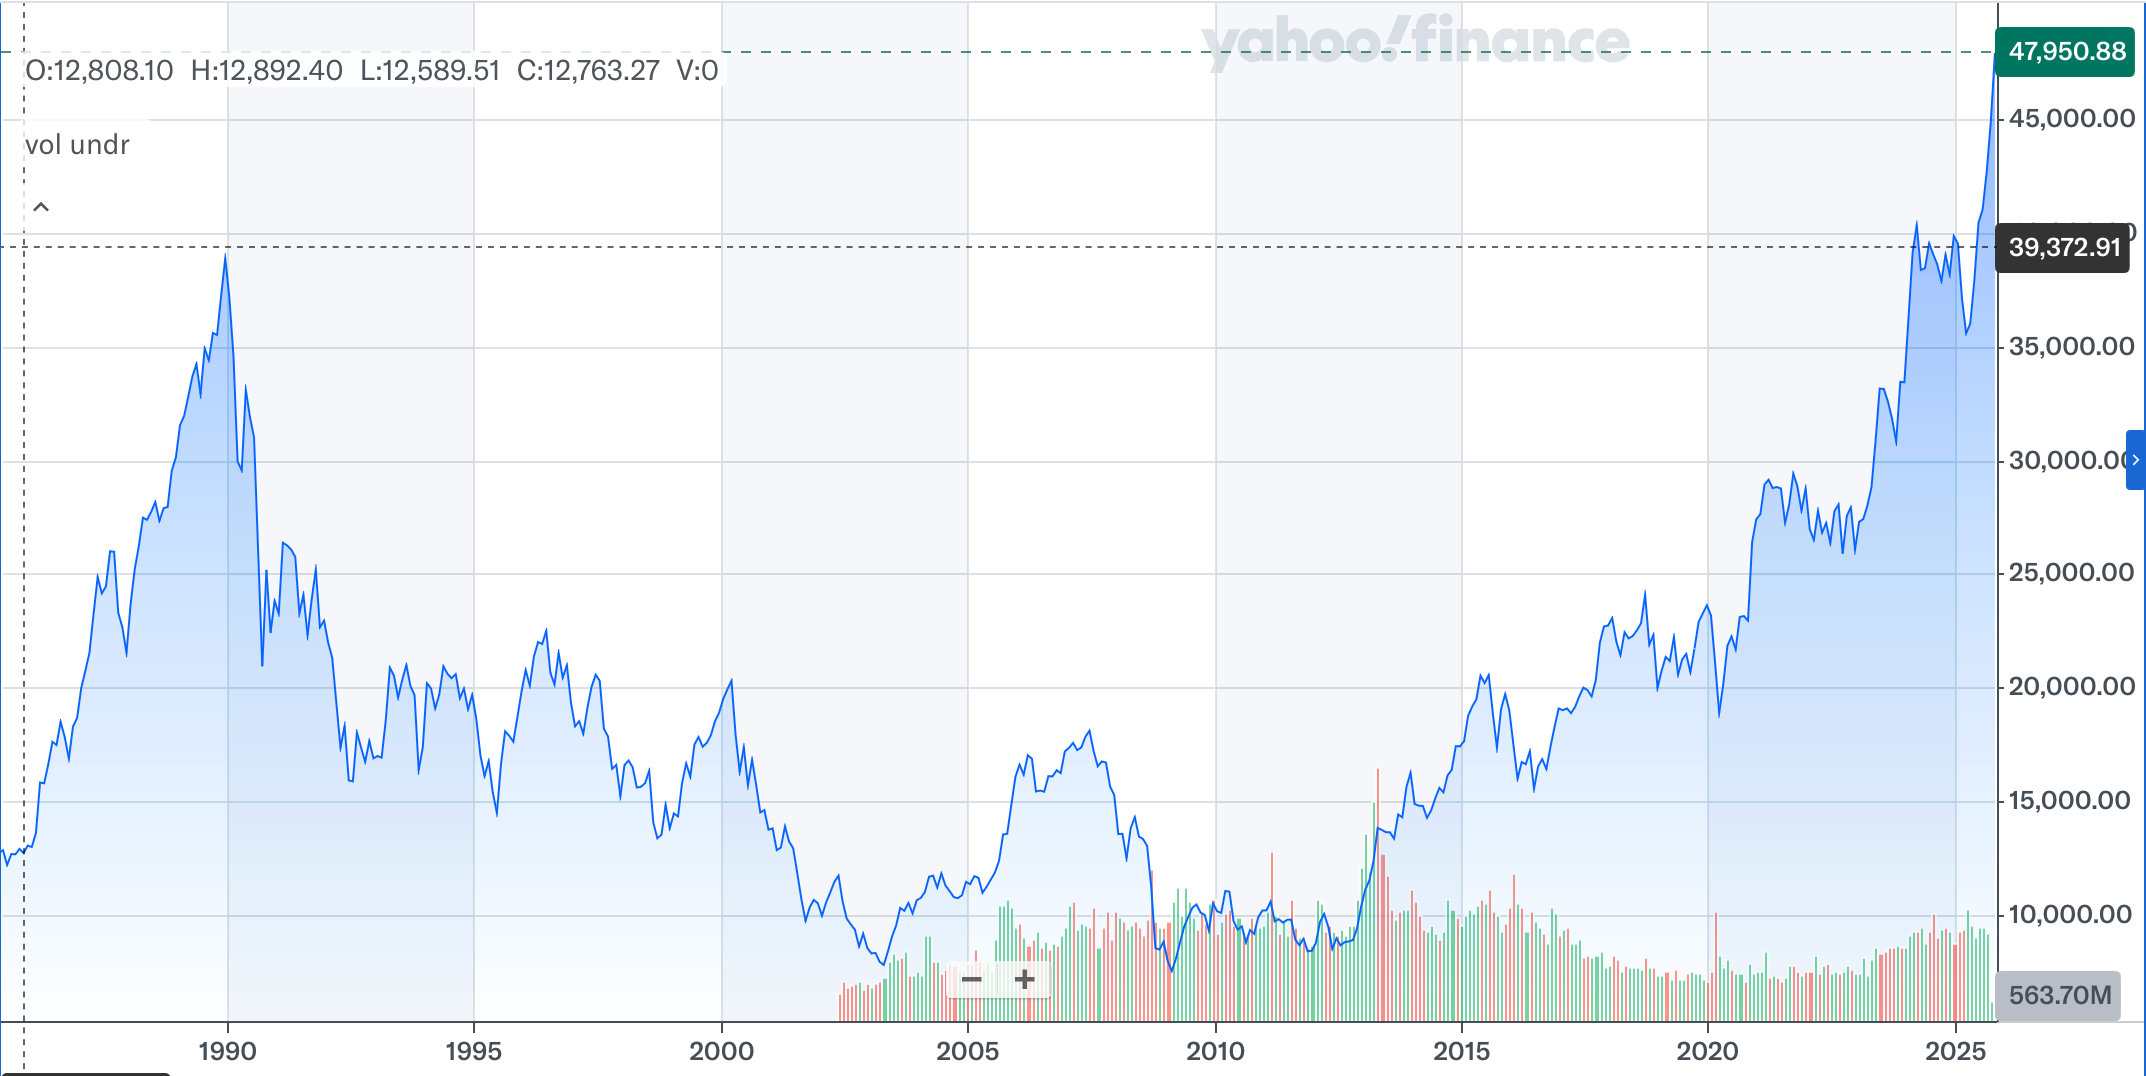
In case you’ve missed it, Japan has been going through “a lost decade” for the past three decades, if that makes any sense. Ever since their stock market bubble burst in 1989, the pain hasn’t really stopped. Since then, slow GDP growth at roughly 1%, deflation that just stuck around, and poor corporate governance kept investors on the sidelines. The Nikkei didn’t hit its 1989 peak again until 2024 (see below). For some perspective, the last time the Nikkei was at this level, the Berlin Wall was still up.
That all started changing with Shinzo Abe’s “Abenomics” in the early 2010s. His playbook was fairly straightforward: introduce QE, flexible fiscal policy (like investing in infrastructure to boost growth), and deregulation. Basically, throw everything at deflation and try to get the economy moving again. It was a solid foundation, but for reasons still debated, it didn’t work as intended...at least not right away.
Fast forward a decade. COVID broke supply chains and created global inflation that hit Japan too. The population kept shrinking, labor got scarce, and unions actually managed to negotiate real wage increases with major employers. Interest rates stayed below zero for almost a decade, and then near zero after that, which kept the yen weak. That helped exporters and boosted corporate profits. Then something interesting happened with governance: management finally stopped sitting on mountains of cash and either reinvested it or gave it back to shareholders through dividends and buybacks. Even Warren Buffett noticed. He took large positions in Japanese trading houses, which the market interpreted as a signal that Japan was back in business.
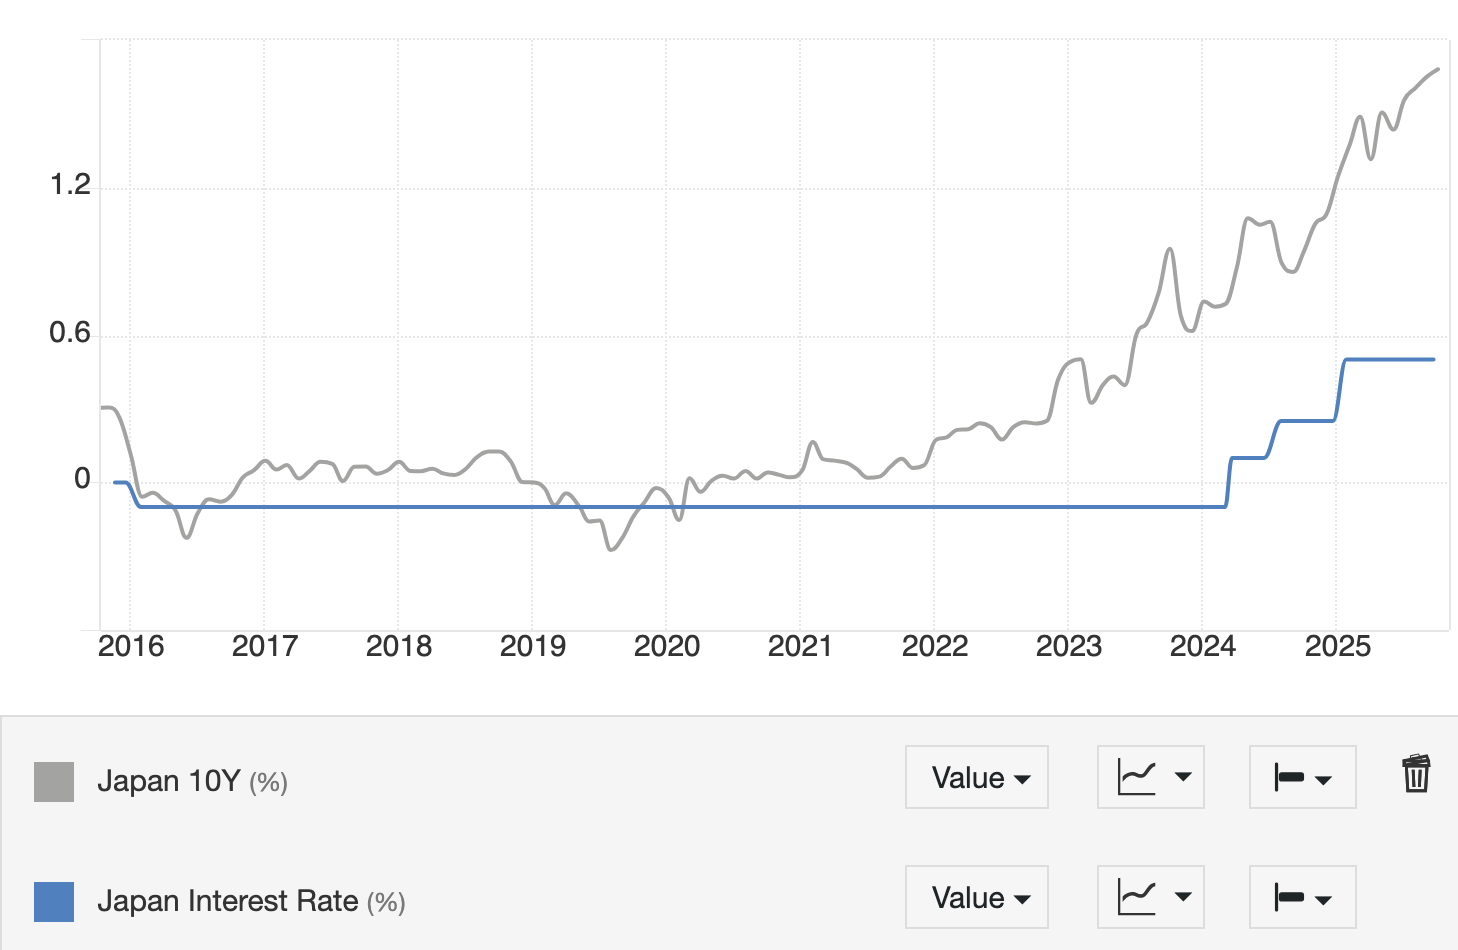
By the end of 2024, Japan started raising rates. They are at 0.50% now. Doesn’t sound like much, but remember these were near or below zero for most of the past 30 years. The yield curve finally normalized, as you can see in the chart below.
What else has changed? Well, real estate prices have been growing rapidly (not going to add another chart - just trust me) and tourism is booming. This Bloomberg article (LINK - Subscription required) suggests that Japan has more visitors a month than it had in a year back in the 2000s.
Ok, this was a very long introduction to why Private Credit is interested in Japan. Let’s see what Financial Times and KKR have to say:
Japan has long been a market where private credit — a term covering a wide range of non-bank lending that is not publicly traded — was not needed due to plentiful, cheap bank funding during years of negative or zero interest rates. That meant funds such as KKR had little chance of making the kinds of returns they deemed necessary to justify the risks. But that has been changing as Japan has exited deflation, the central bank has started increasing interest rates into positive territory and foreign funds have piled into the country doing more of buyouts and building connections with companies.
Diane Raposio (KKR Asia) sees in Japan many of the same conditions that led to a boom in private credit in the US following the global financial crisis. Corporate governance reforms, aimed at improving returns for shareholders, have led some founders to look for ways to delist. For those who do not want to sell to private equity, and with local banks hitting limits on how much they can fund, some companies are starting to look for other sources of financing for a management buyout.
Alright, that is a pretty clear case. Another very important reason is...source of funds. Japan is actually one of the largest insurance markets in the world.
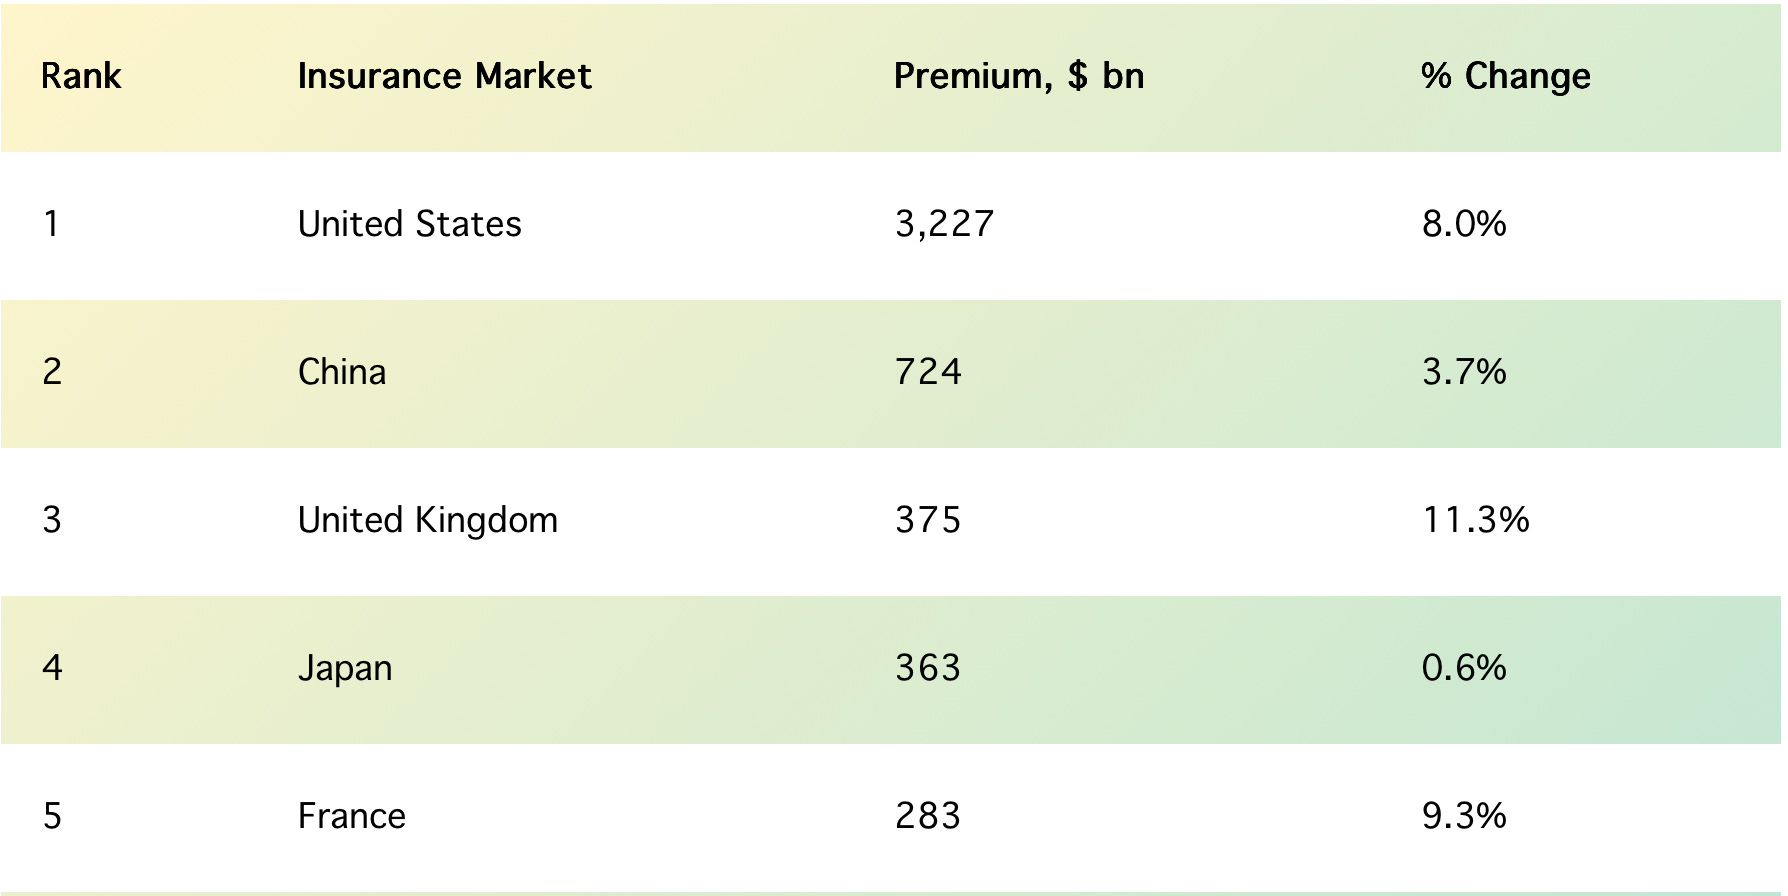
And we all know the relationship between private credit and insurance...Correct - private credit is the reason why insurance companies will get in trouble one day, but until that day comes, they will generate juicier returns than if they invested in their 1.7% yielding 10-year government bonds.
Moving on.
4. US: Debt Spiral
A few days ago, I read what might be the best piece on US debt I’ve encountered...maybe ever? Sounds hyperbolic, but it’s somewhat personal too. It was written by David Rubenstein, Co-Founder of Carlyle: US Debt, Deficits, and the Missed Opportunity (Free LINK).
David is actually a very interesting character who used to serve in Jimmy Carter’s administration before launching Carlyle. He is a prominent collector of America’s historic documents and clearly obsessed with US history (he even wrote a book and runs a podcast about it), so his perspective was worth hearing.
First thing that resonated with me: he admits he doesn’t know what happens if debt keeps growing. I can’t tell you how many times I’ve talked to people obsessed with rising debt who, when pressed, can’t articulate what it actually leads to. Back to my prior post on the Private Credit Bubble, I’m not buying the “it’s very bad” argument until someone clearly lays out what domino falls first and how it spreads. Same with US debt. Here is David’s quote:
So, what will happen when the debt gets closer to the $50 or $60 trillion level in the next decade? No one really knows. The sky-is-falling-soon predictions have not proven accurate over the past few decades.
Second, David goes into the history. Apparently the US has carried government debt since its founding, with only a brief moment in 1835 when Andrew Jackson paid it off because he hated it. David then walks through how debt has gradually grown under both parties, reaching its current level of $37T. Given the lack of political will to tackle it, it’ll only keep growing. BTW, apparently the idea that we can cut taxes to stimulate growth that would cover the deficit is mathematically impossible when you factor in economic fundamentals. So there’s that.
So, the US Government generates $5T in revenue but spends $7T, which obviously results in a $2T annual deficit. $900B of that is interest payments on the debt. The only way the government covers the interest is by issuing more debt.
In a funny way, this is like a Synthetic Delayed Draw Term Loan in private credit. If you are not familiar, Synthetic DDTL is a debt facility that a lender provides to a borrower to cover debt service on existing debt. It’s often used in growth companies that temporarily burn cash (presumably temporarily). Luckily, unlike growth companies, there is no incurrence test for the US Government to draw on that DDTL, although there is that fake maximum incurred debt covenant (the Debt Ceiling) that somehow always gets amended.
Anyway, this essay is an absolute MUST READ.
5. For Fact’s Sake
This snapshot has been all over social media because it’s the kind of thing that gets people talking. I actually shared it myself, since I knew it would get some reactions, and honestly, I need my dose of dopamine from likes and comments.
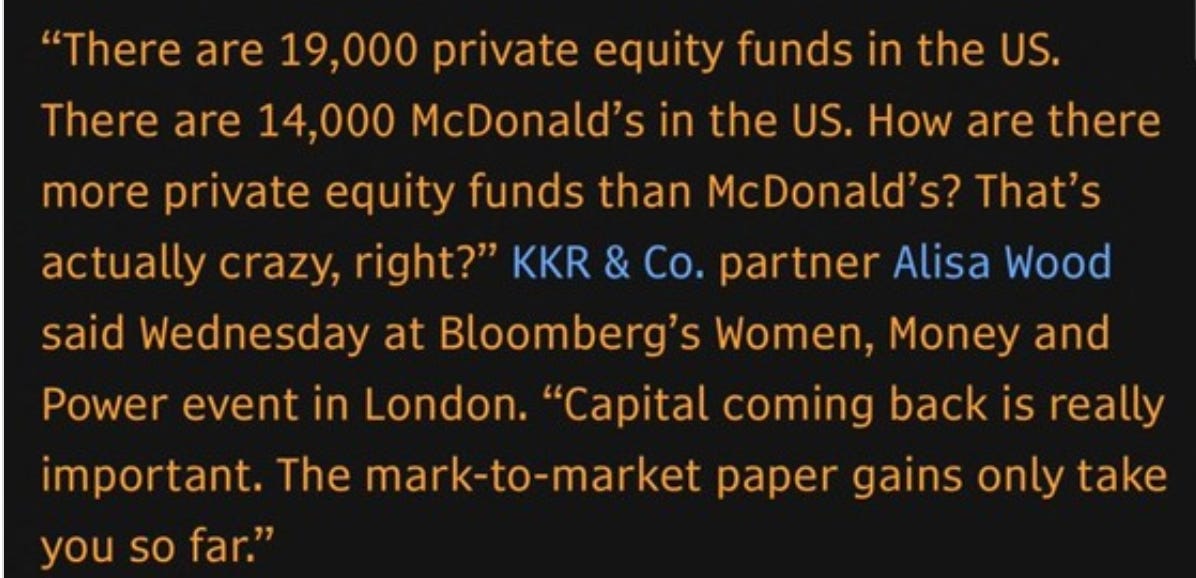
Frankly, I initially misread this post, thinking there are 19,000 PE firms, which didn’t make sense to me. Not because I had the actual statistics, but because I know that PEs like to name themselves after Greek gods (Apollo, Ares, Cerberus*, whatever), and there are just not enough mythical creatures for that many firms, even when you add Roman mythology. Then I realized that it says “funds,” which makes more sense, because some PE firms have dozens of funds. It made even more sense when, after research, I learned that the number likely includes Buyout, Growth Equity, Venture Capital, and other types of organizations. Somehow, VC never comes to mind when someone says PE...like, if you don’t know how to build an LBO model, you should not be called a PE. And let’s be honest, most VCs don’t even know there is such a thing as a Statement of Cash Flows, so no, they wouldn’t be able to build an LBO model.
The reason I cared…I actually don’t know why I cared. Perhaps, because I’ve got sensitive to click-baits, and I like testing them using logic and math. So, I checked.
According to Financial Times (LINK-Subscription required), there were 6,175 VC firms in the US in 2025 (down from 8,300 in 2021), and a bunch of them also have multiple funds. So, we are on the right track. Then I saw this chart from Preqin (should have started with it to save a step) that shows there are 1,104 Buyout and 914 Growth funds (close cousins). Here we go: we went from 19,000 to 2,000 funds that actually sort of compete with one another (although for companies at different stages). Feeling better…
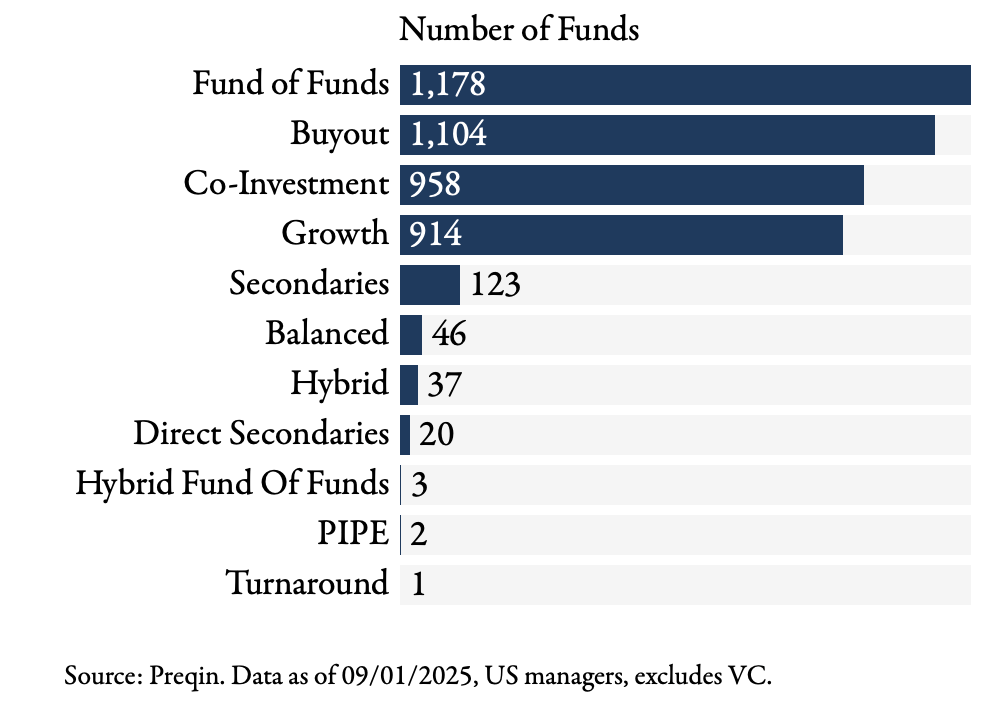
But to be fair, it is still probably 1,990 too many…
* I know Cerberus isn’t a god, but it just flows better…you Classics nerd.
6. Morgan Stanley’s Naptime Narrator
After digging into bankruptcy filings, studying Japan’s and US financial history, and going down some PE-count rabbit hole, it’s refreshing to just read something even toddlers could get. So, here’s basically Private Credit 101 from Morgan Stanley’s head of private credit (Free LINK). Despite simplicity, there are a few interesting charts and commentary:
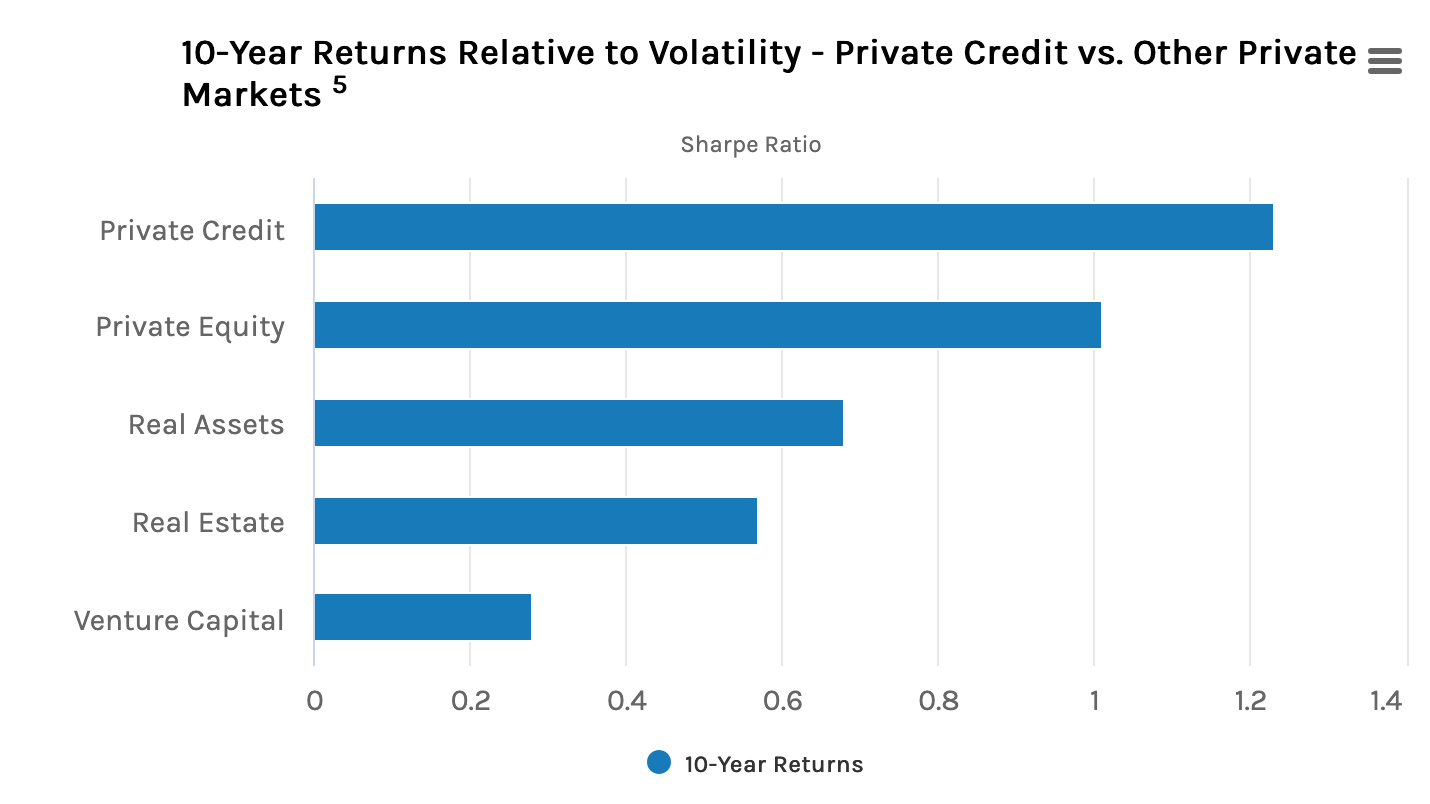
Private credit tends to outperform in rising-rate environments, owing to its floating rate loans. During seven periods of rising rates since 2008, returns in direct lending (private credit’s largest strategy) averaged 11.6% - two percentage points above its long-term average. Above-average performance can also be achieved during a period of moderately declining interest rates. Direct lending posted an annualized return of 10.5% in the fourth quarter of 2024, beating high-yield bonds and leveraged loans, even while the Federal Reserve was cutting rates. If the next set of Fed cuts is shallow, or 100 to 150 basis points in total, that may be an environment in which private credit can continue to deliver compelling returns.
Yeah, if you are an LP who doesn’t care about negative headlines lately, private credit seems like a no-brainer…
7. AIMA’s PC Trend Report
Well, if you thought that Q&A was too elementary, how about this new more sophisticated study by AIMA: Trends in Private Credit Funds Structuring (Free LINK). Here are some key points:
LPs are really ramping up their push for liquidity: 64% say they want more ways to get their cash out, up from 49% two years ago.
Co-investment is having a true moment: demand shot up from 70% to a massive 92% between 2023 and 2025. Investors require more tailored exposures, which is fueling a big wave of SMAs, side letters, and co-investment sleeves across the industry.
The era of mini-SMAs is fading fast: only 6% of managers are willing to do a single-account vehicle for less than $50 million today, down sharply from 23% just two years back.
Leverage is still steady and moderate: About 72% of managers say they use leverage, either at the fund or deal level.
Retail is in the mix in a big way: 57% of managers already have retail clients, with 64% planning to chase even more retail capital with new funds. Most of that flow is coming from HNW and “semi-pro” investors, but more managers are starting to dip their toes into the broader retail pool.
Insurance money is getting more sophisticated: while plenty of insurers stick to classic fund or feeder models, 63% of U.S.-focused managers are exploring rated note feeders, with 35% doing the same for Euro and Asian insurers.
8. En-CLO-sed Resilience
I skipped podcasting section in the past few Rounds, because honestly, I didn’t think there were strong episodes. I liked the recent episode of Credit Edge, whose title reveals some of the key points: CLOs Are Tough to Blow Up, Crescent Says (Free LINK).
Here are a few highlights:
Sentiment is gloomy while the data is generally fine, and key metrics for levered borrowers are actually okay. JPMorgan showed that average leverage for high yield borrowers is around 4x - the lowest in 20 years. Most people don’t know that. You’d think we’re heading off a cliff, but the data doesn’t support it. There are vulnerable sectors, but overall leverage is in good shape.
High yield has shrunk, but that has been offset by private credit and leveraged loans growing way faster. As a side effect, high yield’s average credit rating is higher than it has ever been. People wonder why spreads are so tight. High yield and investment grade have basically converged. High yield averages BB, investment grade averages BBB, so they are closer than ever in both rating and spread. That means the market is pretty efficient.
Some say defaults are elevated, but given the rate hiking cycle since 2022, they’re still only in line with long-term averages. That said, there’s complacency. Private credit has raised massive capital, and investment grade has seen strong inflows.
Practitioners and investors use the terms CLO 1.0 and CLO 2.0 to refer to CLO structures before and after the Great Financial Crisis. After the crisis, many important changes were made to strengthen and improve the safety of these deals. Nothing is completely risk-free, but these updates have made CLOs tougher. This is why investors can still earn mid to high single digit yields.
Private credit CLOs represent 20% of new market issuance in recent years, while several years ago it was close to zero. Investors find them attractive because they offer higher spreads—about 25 to 50 basis points above BSL CLOs. For example, AAA middle market CLO tranches yield about 5.5%, while BBB tranches yield about 7.5%, which is much higher than investment grade corporate bonds.
9. Deals on the Block
(click active links for additional details)
Lender: PNC Bank - Agent (Truist, Regions, U.S. Bank, others)
Borrower: NETSTREIT
Sponsor: N/A - REIT
Facility: $450m
$200m Unsecured 5.5-year Term Loan, priced at SOFR + 1.15% to 1.60% (leverage-based grid)
$100m Unsecured 7-year Term Loan, priced at SOFR + 1.50% to 2.20% (leverage-based grid)
$150m Unsecured 7-year Delayed Draw Term Loan, priced at SOFR + 1.50% to 2.20%, and to be drawn within 1 year.
Purpose: Growth financing and general purposes
Borrower: Verano Holdings
Sponsor: N/A (Public)
Facility: $75m Revolver (3-year facility)
Pricing: SOFR + 6.00%
Purpose: Upsize from $50m
Lender: Deutsche Bank, Barclays, et al
Borrower: EdgePoint Infrastructure
Sponsor: DigitalBridge and Abu Dhabi Investment Authority
Facility: $475m (5-year facility)
Pricing: SOFR + 4.00%
Purpose: Dividend recap
Other: Private credit declined due to pricing
Lender: First Horizon Bank, Flagstar, and Cadence Bank
Borrower: Standard Premium Finance
Sponsor: N/A (Public)
Facility: $75m Revolver
Pricing: SOFR + 2.15%
Purpose: Repricing
Other: Pricing was reduced from SOFR + 2.55%, and maturity was extended. Media reports mention an additional $40m of uncommitted accordion, which is nonsense—anytime you see “uncommitted,” assume it doesn’t exist.
Borrower: Alliance Entertainment
Sponsor: N/A (Public)
Facility: $120m Revolver (5-year facility)
Pricing: SOFR + 1.50% to 1.625%
Purpose: Refinancing existing private credit from White Oak
Just to be clear: more deals surfaced, but I only flagged ones with details beyond size (pricing, attachment, etc.). If you catch wind of more, send them over - anonymity guaranteed.
That’s the bell — round over. See you in the next.
Aznaur Midov
aznaur@yahoo.com
BTW, 81 lenders also means a lot of law firms, and legal fees. By the time the roll call wraps up and everyone has confirmed they are on the line, lawyers are already well in the green. Good times!
too funny.
This newsletter is REALLY good, very insightful, going to recommend it to the NYU Stern community!